Student Loan Forgiveness 2026: Eligibility Updates Explained
Advertisements
Understanding the nuanced 3-month eligibility updates for student loan forgiveness programs in 2026 is critical for borrowers navigating federal debt relief options and securing their financial future.
Navigating the complex landscape of federal student loan programs can be challenging, especially with ongoing changes. This article provides a deep dive into the latest 3-month eligibility updates for student loan forgiveness programs in 2026, offering clarity and guidance for borrowers seeking debt relief. We’ll explore who qualifies, what documentation is needed, and how these changes might impact your financial future.
Understanding the Evolution of Student Loan Forgiveness
Student loan forgiveness programs have undergone significant transformations over the past few years, reflecting shifts in economic policy and societal needs. These programs are designed to alleviate the burden of educational debt, providing a pathway to financial stability for millions of Americans. As we approach 2026, new adjustments are being implemented, particularly concerning eligibility criteria over specific periods.
Historically, forgiveness initiatives have targeted various groups, including public service workers, teachers, and individuals experiencing financial hardship. Each program typically has its own set of requirements, repayment milestones, and application processes. Staying informed about these evolving details is crucial for anyone hoping to benefit from these opportunities.
Key Historical Forgiveness Programs
- Public Service Loan Forgiveness (PSLF): Designed for individuals working full-time for qualifying non-profit organizations or government agencies.
- Teacher Loan Forgiveness: Offers forgiveness to eligible teachers who work for five consecutive years in low-income schools or educational service agencies.
- Income-Driven Repayment (IDR) Plan Forgiveness: After 20 or 25 years of payments under an IDR plan, any remaining balance can be forgiven.
These programs serve as cornerstones, but their rules and implementation often see modifications. The 2026 updates build upon these existing frameworks, refining who can access relief and under what conditions.
The continuous evolution of student loan forgiveness reflects a dynamic approach to addressing student debt. Borrowers must remain vigilant, regularly checking official government sources for the most current information. Understanding the historical context helps to better grasp the rationale behind the upcoming changes and how they might affect individual eligibility.
The Latest 3-Month Eligibility Updates for 2026
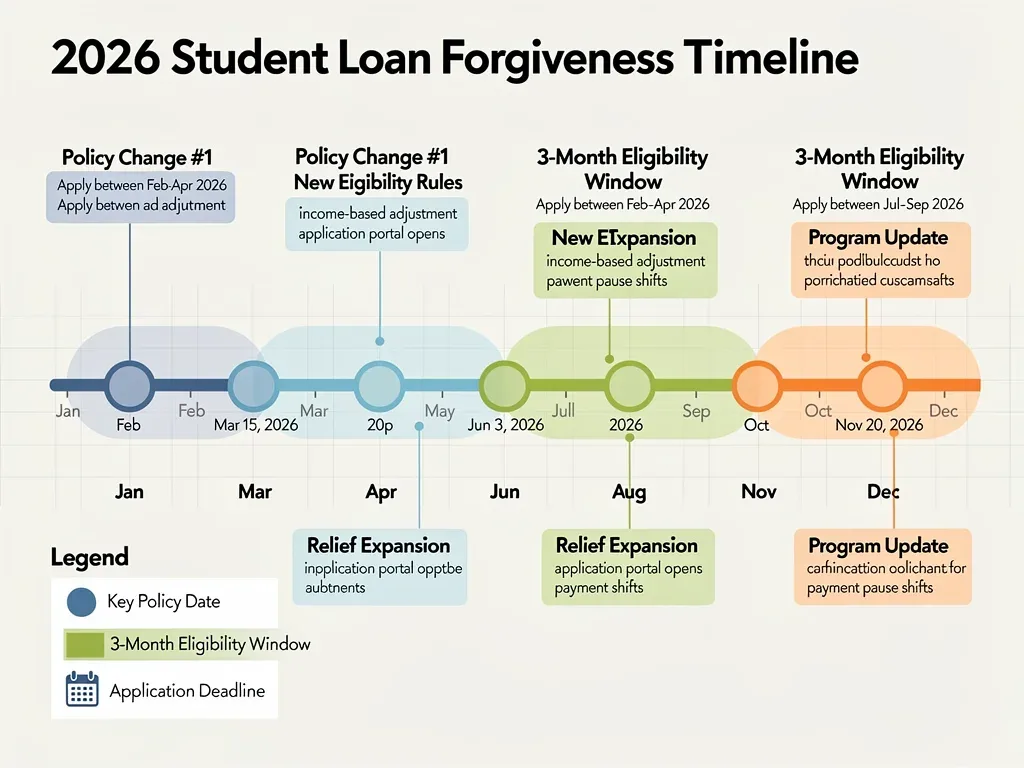
As 2026 approaches, new eligibility updates are being introduced for several key student loan forgiveness programs, with a particular focus on a specific 3-month window. These updates aim to streamline processes, expand access for certain borrower groups, and clarify existing requirements. Understanding these changes is paramount for borrowers planning to apply or reassess their eligibility.
The core of these updates revolves around a specific 3-month period that will be crucial for determining eligibility for various forgiveness initiatives. This period might relate to loan status, payment history, or employment verification. It’s essential to identify this window and ensure all necessary documentation and actions are completed within it.
Specific Program Adjustments
Several programs are seeing modifications. For example, some Public Service Loan Forgiveness (PSLF) applicants might find a temporary waiver or credit applied to past payments made during this 3-month period, even if they didn’t initially meet all criteria. This could significantly broaden the pool of eligible borrowers.
- PSLF Expansion: Temporary changes might count previously ineligible payments or periods towards the 120 required payments.
- IDR Recalibration: Adjustments to income-driven repayment plans could offer a one-time payment count adjustment for certain borrowers, potentially accelerating forgiveness.
- Targeted Forgiveness: New initiatives might specifically target borrowers in particular professions or those who faced prolonged economic hardship during this defined 3-month period.
These adjustments are not arbitrary; they are often a response to economic trends, feedback from borrowers, and ongoing efforts to make the federal student aid system more equitable. The 3-month window provides a concentrated opportunity for borrowers to review their circumstances and take advantage of these updated criteria. It is highly recommended to consult the official Department of Education website or a trusted financial advisor to confirm how these specific changes apply to your individual loan portfolio.
Who Qualifies: Detailed Criteria and Conditions
Determining who qualifies for student loan forgiveness programs in 2026, especially with the new 3-month eligibility updates, requires a close look at detailed criteria and conditions. Eligibility is not a one-size-fits-all scenario; it depends heavily on your loan type, employment history, income level, and past repayment behavior. These new updates often introduce specific windows or conditions that might make previously ineligible borrowers now qualify.
The primary factor for many forgiveness programs remains the type of federal loan you hold. Generally, Direct Loans are the most eligible, while Federal Family Education Loans (FFEL) or Perkins Loans often require consolidation into a Direct Loan to qualify. The 3-month eligibility updates may simplify this consolidation process or offer retroactive credit for certain payments made on non-Direct Loans.
Employment and Service Requirements
For programs like PSLF or Teacher Loan Forgiveness, specific employment criteria are paramount. For PSLF, you must work full-time for a qualifying employer, which includes government organizations at any level (federal, state, local, or tribal) and not-for-profit organizations that are tax-exempt under Section 501(c)(3) of the Internal Revenue Code. The 3-month window might involve a specific period of employment verification or a waiver for temporary employment gaps.
- Full-time Employment: Generally defined as 30 hours per week or more.
- Qualifying Employer: Government agencies and 501(c)(3) non-profits.
- Service Period: A minimum number of years or payments (e.g., 120 payments for PSLF).
Income-Driven Repayment (IDR) plan forgiveness, on the other hand, primarily focuses on your income and family size, ensuring your monthly payments are affordable. After 20 or 25 years of payments, any remaining balance is forgiven. The 3-month updates might affect how past payments are counted towards this lengthy period, potentially offering a credit for periods of forbearance or deferment.
It’s crucial to understand that these programs are not automatic. Borrowers must actively apply and often recertify their eligibility annually. The 2026 updates might introduce new forms or a simplified application process for those falling within the specific 3-month eligibility window. Regularly checking the official Federal Student Aid website (StudentAid.gov) is the best way to ensure you have the most accurate and up-to-date information regarding your specific situation and how to proceed.
Navigating the Application Process and Documentation
Successfully applying for student loan forgiveness, especially with the new 3-month eligibility updates in 2026, hinges on meticulous attention to the application process and thorough documentation. The process can seem daunting, but breaking it down into manageable steps can help ensure a smooth submission. These updates might introduce specific deadlines or new forms that require immediate attention.
The first step is always to identify which forgiveness program you might qualify for. Once you’ve determined the most suitable program based on your loan type and employment, gather all necessary documents. This typically includes proof of employment, income verification, and records of your loan payments. The 3-month eligibility window may require specific documentation related to that period, such as pay stubs or employment verification letters.
Essential Documentation Checklist
Having your documents organized and ready can significantly expedite your application. Here’s a general checklist:
- Employment Certification Forms: Especially for PSLF, these forms must be completed by your employer.
- Tax Returns: Used for income verification, particularly for IDR plans.
- Loan Statements: Records of your loan balances and payment history.
- Proof of Graduation/Enrollment: Required for some targeted forgiveness programs.
The 2026 updates might introduce a specific portal or submission method for applications falling under the 3-month eligibility criteria. It’s vital to follow these instructions precisely. Incomplete applications are a common reason for delays or rejections. Double-check every field and ensure all required signatures are obtained.
Once submitted, keep copies of everything for your records. The processing time can vary, so patience is key. If you encounter any issues or have questions, contact your loan servicer or the Federal Student Aid Information Center. They can provide clarification on the new updates and guide you through any complexities. Proactive engagement with the application process and careful document management are your best allies in securing student loan forgiveness.
Impact of the 3-Month Updates on Different Borrower Groups
The 3-month eligibility updates for student loan forgiveness programs in 2026 are poised to have varied impacts across different borrower groups. While some may find new avenues for relief, others might need to adjust their strategies. Understanding how these changes specifically affect categories like public servants, low-income earners, and those with older loans is crucial for anticipating outcomes and planning accordingly.
For public service workers, the updates could be particularly beneficial. If the 3-month window allows for retroactive credit for certain payments or periods of employment that were previously deemed ineligible, many dedicated individuals who have served their communities could finally see their PSLF journey accelerated. This could translate into earlier forgiveness and significant financial relief.
Effects on Low-Income Borrowers
Low-income borrowers, who often rely on Income-Driven Repayment (IDR) plans, might also experience positive changes. The 3-month updates could include adjustments to how payments are counted, potentially reducing the overall time required to reach forgiveness under IDR plans. This would provide a much-needed boost to those struggling with affordability.
- Accelerated Forgiveness: Shorter repayment timelines due to revised payment counting.
- Reduced Monthly Burdens: Potentially lower payments if income thresholds are adjusted.
- Expanded Access: More flexibility for those with fluctuating incomes.
Borrowers with older loans, especially those who had FFEL or Perkins Loans, might find the consolidation process into Direct Loans simplified or receive more generous credit for past payments during the specified 3-month period. This could be a game-changer for individuals who felt excluded from previous forgiveness efforts due to their loan type. Conversely, some borrowers who were already on track for forgiveness might see minimal change, as the updates primarily target specific gaps or areas of improvement within the existing framework.
Ultimately, the impact is highly individualized. It is essential for each borrower to review their specific loan details, employment history, and financial situation against the new 2026 guidelines. Engaging with a financial counselor or directly with your loan servicer can help clarify how these updates will specifically shape your path to student loan forgiveness.
Planning for 2026: Tips and Best Practices
As 2026 approaches with its new 3-month eligibility updates for student loan forgiveness, proactive planning and adherence to best practices are essential for maximizing your chances of securing debt relief. Don’t wait until the last minute; understanding the potential changes and preparing your finances now can make a significant difference. This forward-thinking approach will ensure you are well-positioned to take advantage of any opportunities that arise.
One of the most critical steps is to regularly monitor official government sources, such as StudentAid.gov, for the latest announcements. Program details can change, and being informed early allows you to adapt your strategy. Set up alerts or subscribe to newsletters that provide updates on federal student aid policies. This ensures you won’t miss any crucial deadlines related to the 3-month eligibility window.
Financial Health and Documentation
Beyond staying informed, focus on your overall financial health and meticulous record-keeping. Ensure your contact information with your loan servicer is always up to date. Keep an organized file, either physical or digital, of all loan documents, payment histories, and employment verification forms. This will be invaluable when applying for forgiveness or responding to any requests for additional information.
- Verify Loan Type: Confirm your loan types are eligible or consider consolidation if necessary.
- Update Contact Info: Ensure your loan servicer has your current address, email, and phone number.
- Maintain Records: Keep all employment and payment documentation in an accessible place.
Consider consulting with a qualified financial advisor who specializes in student loans. They can provide personalized guidance, help you understand the nuances of the 2026 updates, and assist with navigating the application process. An expert can also help you evaluate alternative repayment strategies or explore other debt relief options if forgiveness doesn’t fully meet your needs.
Finally, be prepared to act swiftly once the specific details of the 3-month eligibility window are officially released. Gather any necessary forms, obtain employer signatures, and submit your application promptly. Proactive preparation, continuous monitoring, and expert advice are your strongest tools in successfully navigating the complexities of student loan forgiveness in 2026.
The Future Outlook for Student Loan Forgiveness Beyond 2026
While the focus is currently on the student loan forgiveness programs in 2026 and their specific 3-month eligibility updates, it’s also important to consider the long-term outlook for student debt relief. The landscape of federal student aid is constantly evolving, influenced by political shifts, economic conditions, and ongoing debates about higher education funding. Understanding these broader trends can help borrowers anticipate future changes and plan their financial strategies effectively.
Policy discussions often revolve around making college more affordable, simplifying repayment plans, and providing targeted relief to specific groups. It’s likely that future iterations of forgiveness programs will continue to refine these goals, potentially introducing new criteria or expanding existing benefits. However, it’s also possible that some programs could face stricter eligibility requirements or even be phased out, depending on legislative priorities.
Potential Policy Directions
- Universal Loan Forgiveness: While highly debated, the concept of broad-based forgiveness remains a possibility, though its implementation faces significant political and economic hurdles.
- Streamlined IDR Plans: Efforts to simplify and improve Income-Driven Repayment plans are ongoing, aiming for clearer paths to forgiveness and reduced administrative burdens.
- Targeted Relief: Future programs may increasingly focus on specific demographics, such as low-income borrowers, those in critical public service roles, or individuals with disabilities.
The 3-month eligibility updates in 2026 can be seen as a stepping stone in this continuous evolution, a response to immediate needs and a test of new approaches. Borrowers should not view any current program as set in stone indefinitely. Instead, maintaining an adaptive mindset and staying informed about legislative developments will be key.
For those currently repaying loans, the best strategy involves maximizing present opportunities while preparing for potential future changes. This means making qualifying payments, keeping accurate records, and exploring all available options. The future of student loan forgiveness is dynamic, and staying engaged with the conversation will empower borrowers to make informed decisions about their financial well-being.
| Key Point | Brief Description |
|---|---|
| 3-Month Eligibility Window | A specific period in 2026 where new or adjusted criteria apply for certain forgiveness programs. |
| Loan Type Importance | Direct Loans are typically most eligible; FFEL/Perkins often require consolidation. |
| Documentation is Key | Accurate records of employment, income, and payments are crucial for application. |
| Proactive Planning | Stay informed, monitor official sources, and consult advisors for personalized guidance. |
Frequently Asked Questions About 2026 Student Loan Forgiveness
What exactly is the 3-month eligibility update for 2026?▼The 3-month eligibility update refers to specific adjustments in student loan forgiveness criteria that will apply during a designated three-month period in 2026. These changes might include retroactive payment credits, simplified application processes, or expanded eligibility for certain borrower groups, aiming to provide targeted relief and streamline access to forgiveness programs.
Which loan types are most likely to benefit from these 2026 updates?▼Federal Direct Loans are typically the most eligible for forgiveness programs. However, the 2026 updates might specifically benefit borrowers with Federal Family Education Loans (FFEL) or Perkins Loans by offering more favorable terms for consolidation into Direct Loans, making them eligible for programs like PSLF or IDR forgiveness.
Do I need to reapply for forgiveness if I’m already on an IDR plan?▼While you typically need to recertify your income and family size annually for IDR plans, the 2026 updates might introduce a specific reapplication or review process to take advantage of new payment counting adjustments. It’s crucial to monitor official communications from your loan servicer and StudentAid.gov for precise instructions.
What kind of documentation should I prepare for the 2026 updates?▼You should prepare comprehensive documentation including employment certification forms (if applicable), tax returns, loan statements showing payment history, and any records verifying your income or periods of economic hardship. Specific requirements for the 3-month window will be detailed in official guidance, so stay informed.
Where can I find the most accurate and up-to-date information?▼The most accurate and up-to-date information regarding student loan forgiveness programs and the 2026 eligibility updates will always be available on the official Federal Student Aid website (StudentAid.gov). You should also regularly check communications from your specific student loan servicer for personalized updates.
Conclusion
The student loan forgiveness programs in 2026, particularly with the introduction of the 3-month eligibility updates, represent a critical period for millions of borrowers seeking relief from educational debt. These changes underscore the government’s ongoing commitment to refining and expanding access to forgiveness, though navigating the complexities requires diligence and proactive engagement. By understanding the detailed criteria, meticulously preparing documentation, and staying informed through official channels, borrowers can effectively position themselves to benefit from these evolving opportunities. The path to debt relief may be intricate, but with careful planning and adherence to best practices, the promise of a more stable financial future remains within reach.