Inflation’s Impact on 2026 Retirement: Combat 3.5% Erosion
Advertisements
A 3.5% inflation rate can significantly diminish the purchasing power of your 2026 retirement savings, necessitating proactive financial strategies to mitigate erosion and preserve your future financial security.
Are you looking ahead to your retirement in 2026? It’s a milestone many anticipate, but a quiet threat could be undermining your financial security: inflation. Specifically,
the impact of inflation on your 2026 retirement savings: strategies to combat a 3.5% erosion is a critical topic that demands immediate attention to ensure your hard-earned money retains its value.
Understanding the Silent Threat of Inflation on Retirement
Inflation, often described as the silent thief of wealth, gradually diminishes the purchasing power of money over time. For those planning to retire in 2026, even a seemingly modest
3.5% annual inflation rate can have a substantial cumulative effect on their retirement savings. This erosion means that the same amount of money will buy significantly less in the future than it does today, directly impacting your quality of life during retirement. Many individuals underestimate the long-term consequences of inflation, focusing more on nominal returns rather than real returns.
The core issue lies in how inflation affects fixed incomes and traditional savings accounts. If your retirement income streams, such as pensions or annuities, are not indexed to inflation, their real value will decline year after year. Similarly, cash held in low-interest savings accounts will lose purchasing power rapidly. Understanding this fundamental concept is the first step toward building a resilient retirement plan. The goal is not just to accumulate wealth, but to ensure that wealth can sustain your desired lifestyle. Ignoring inflation is akin to planning a trip without accounting for fuel costs; it will eventually leave you stranded.
The Real Cost of a 3.5% Inflation Rate
- Erosion of Purchasing Power: A 3.5% inflation rate means that something costing $100 today will cost approximately $103.50 next year. Over a decade, this effect compounds dramatically.
- Impact on Fixed Incomes: Pensions and annuities not adjusted for inflation will see their real value decrease, forcing retirees to cut back on expenses.
- Savings Account Vulnerability: Funds held in traditional savings accounts often yield interest rates below the inflation rate, leading to a net loss in real terms.
- Healthcare Expense Growth: Medical costs typically outpace general inflation, making healthcare a significant concern for retirees facing eroded savings.
The cumulative effect of inflation over a typical 20-30 year retirement period can be staggering. A 3.5% annual erosion might seem small, but it can cut the purchasing power of your savings by more than half over two decades. This necessitates a proactive and well-thought-out strategy to ensure your retirement funds are not just growing, but growing at a pace that outstrips or at least matches the inflation rate. Without such a strategy, many retirees may find their golden years tarnished by financial strain. Therefore, assessing your current financial position and projecting future needs with inflation in mind is paramount.
In conclusion, recognizing inflation as a significant threat to your retirement savings is essential. It’s not enough to simply save; you must save strategically, understanding how the purchasing power of your money can be eroded. A 3.5% inflation rate is a tangible challenge that requires a robust financial defense. By comprehending its mechanisms and potential impact, you can begin to formulate effective countermeasures to protect your future.
Assessing Your Current Retirement Portfolio’s Inflation Resilience
Before implementing new strategies, it’s vital to assess how your existing retirement portfolio stands against inflation. Many portfolios are structured with assumptions that might not hold true in an environment of sustained inflation, particularly if you are targeting retirement in 2026. A thorough review helps identify vulnerabilities and areas where adjustments are most needed. This assessment should go beyond just looking at the nominal value of your assets; it must delve into their real, inflation-adjusted value.
Consider the types of assets you hold. Are they primarily fixed-income investments like bonds or certificates of deposit (CDs)? While these offer stability, their returns often struggle to keep pace with inflation. Equity-heavy portfolios might offer better inflation protection over the long term, but they also come with higher volatility. Real estate and commodities are often cited as inflation hedges, but their performance can vary. A balanced approach involves understanding the inflation-hedging capabilities of each asset class within your portfolio. A critical aspect of this assessment is understanding the time horizon until your retirement, as this influences the level of risk you can comfortably take.
Evaluating Asset Classes for Inflation Protection
- Stocks: Historically, equities have outperformed inflation over long periods, as companies can raise prices to offset increased costs.
- Bonds: Traditional bonds are generally vulnerable to inflation, as rising prices erode the fixed interest payments’ real value. Treasury Inflation-Protected Securities (TIPS) are an exception.
- Real Estate: Property values and rental income often increase with inflation, making real estate a potential hedge, but liquidity can be an issue.
- Commodities: Gold, oil, and other raw materials tend to perform well during inflationary periods, but they can be volatile.
Another crucial aspect of your assessment is to review your projected spending in retirement. Inflation doesn’t affect all expenses equally. Healthcare costs, for instance, tend to rise faster than general inflation. Understanding your likely expenditure categories can help you tailor your portfolio to protect against specific rising costs. This personalized approach ensures your strategies are not generic but instead address your unique financial landscape and future needs. It’s about aligning your investments with your anticipated lifestyle.
In essence, a comprehensive portfolio assessment involves more than just glancing at your statements. It requires a deep dive into the real returns of your assets, their inherent inflation-hedging characteristics, and how they align with your anticipated retirement expenses. By understanding your current position, you can make informed decisions about necessary adjustments to combat the impact of inflation on your 2026 retirement savings.
Diversification and Asset Allocation: Your Inflation Defense
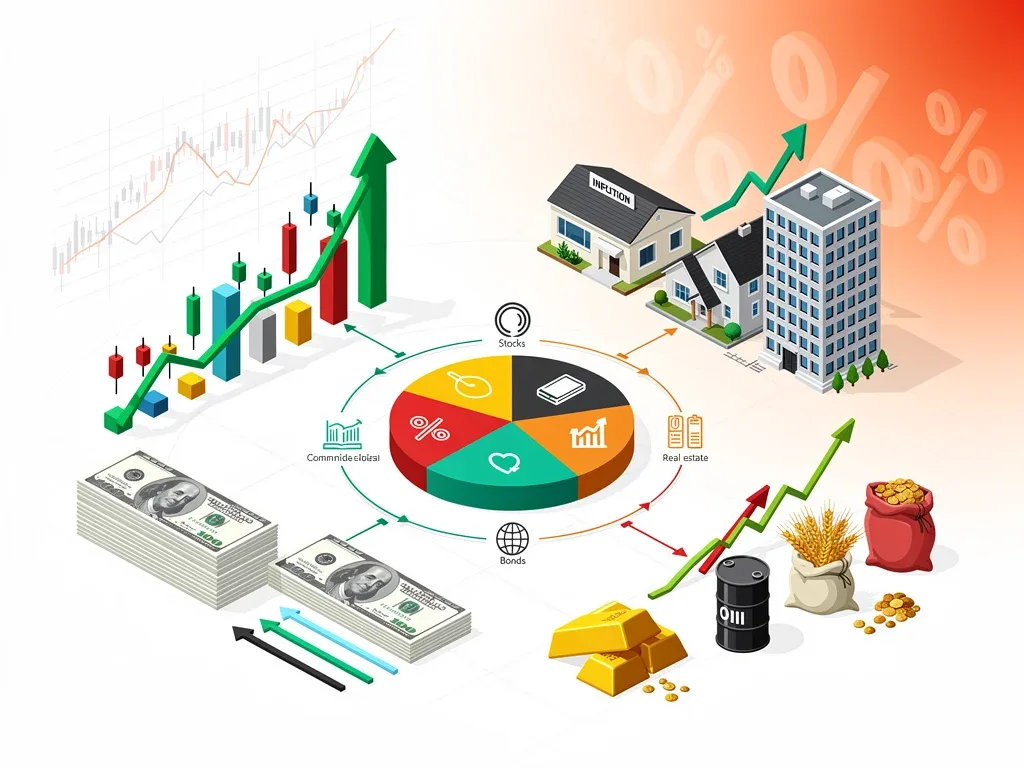
Diversification and strategic asset allocation are cornerstones of any robust investment strategy, but they become particularly critical when facing the threat of inflation. For those anticipating retirement in 2026, a well-diversified portfolio is not just about mitigating risk; it’s about building a defense against the erosion of purchasing power caused by a 3.5% inflation rate. The goal is to spread investments across various asset classes that react differently to inflationary pressures.
Relying too heavily on a single asset class, even one historically considered an inflation hedge, can be risky. A balanced approach involves allocating funds across a mix of equities, real estate, commodities, and inflation-protected securities. This strategy aims to ensure that if one asset class underperforms due to inflation, others may compensate, thereby stabilizing your overall portfolio value. This proactive approach helps to smooth out returns and maintain the real value of your savings over time, which is paramount when facing the impact of inflation on your 2026 retirement savings.
Key Diversification Strategies for Inflation Protection
- Global Equities: Investing in companies across different countries and sectors can provide broader exposure and reduce reliance on any single economy’s performance.
- Real Estate Investment Trusts (REITs): REITs allow you to invest in real estate without directly owning property, offering potential income and capital appreciation that can keep pace with inflation.
- Commodity Exposure: Consider funds or ETFs that invest in commodities like gold, silver, or agricultural products, which often see price increases during inflationary periods.
- Treasury Inflation-Protected Securities (TIPS): These U.S. Treasury bonds are indexed to inflation, meaning their principal value adjusts with the Consumer Price Index (CPI), providing a direct hedge.
Beyond simply diversifying, regular rebalancing of your portfolio is essential. Market conditions change, and inflation rates can fluctuate. Periodically reviewing and adjusting your asset allocation ensures that your portfolio remains aligned with your risk tolerance and inflation-fighting objectives. This dynamic approach prevents your portfolio from drifting away from its intended structure and becoming overly exposed to certain risks. It’s about maintaining an active rather than passive stance towards your investments.
In summary, diversification and strategic asset allocation are not merely buzzwords; they are critical tools in your arsenal against inflation. By thoughtfully spreading your investments across various asset classes with different responses to inflationary pressures, and by regularly rebalancing, you can significantly enhance your portfolio’s resilience and protect the real value of your 2026 retirement savings from erosion.
Considering Inflation-Protected Investments and Income Streams

To directly combat the impact of inflation on your 2026 retirement savings, actively seeking out investments and income streams specifically designed to protect against rising prices is a smart move. While diversification provides a broad defense, certain financial instruments offer a more direct hedge, ensuring your money’s purchasing power is preserved even with a 3.5% inflation rate. These specialized options can be crucial components of a resilient retirement plan.
Treasury Inflation-Protected Securities (TIPS) are perhaps the most well-known inflation-indexed investment. The principal value of TIPS adjusts with the Consumer Price Index (CPI), and the interest payments are then paid on the adjusted principal. This means both your principal and your interest payments grow with inflation, providing a powerful shield. Beyond TIPS, certain annuities can offer inflation riders, though these often come with additional costs. Exploring these options can provide a layer of security that traditional investments might lack, directly addressing the challenge of inflation erosion.
Direct Inflation Hedges to Explore
- Treasury Inflation-Protected Securities (TIPS): Principal and interest payments adjust with inflation, offering direct protection.
- I-Bonds: Series I Savings Bonds offer a combination of a fixed rate and an inflation rate, providing a safe, accessible way to protect savings from inflation.
- Real Estate: Investment properties can generate rental income that typically rises with inflation, and property values often appreciate.
- Commodity Funds: Exchange-Traded Funds (ETFs) or mutual funds focused on commodities can provide exposure to assets that historically perform well during inflationary periods.
- Inflation-Indexed Annuities: Some annuities offer riders that adjust payments based on inflation, though careful review of terms and fees is necessary.
It’s also important to consider income streams that naturally keep pace with inflation. For instance, some pensions or Social Security benefits are inflation-indexed. Understanding how much of your future income will automatically adjust for inflation can help you determine how much additional inflation protection your investment portfolio needs. This holistic view ensures all facets of your retirement finances are working in concert to preserve your purchasing power.
In conclusion, incorporating inflation-protected investments and income streams into your retirement plan is a proactive strategy to safeguard your financial future. By leveraging tools like TIPS, I-Bonds, and carefully selected real estate or annuities, you can directly counter the erosive effects of a 3.5% inflation rate and ensure your 2026 retirement savings maintain their real value.
Optimizing Your Spending and Budgeting for an Inflationary Future
While investment strategies are crucial, optimizing your spending and budgeting habits is equally important in combating the impact of inflation on your 2026 retirement savings. A 3.5% inflation rate means your daily expenses will gradually increase, making efficient money management an indispensable skill. Proactive budgeting allows you to identify areas where you can reduce costs or make more value-driven choices, thereby stretching your retirement dollars further.
Start by creating a detailed budget that reflects your anticipated retirement lifestyle. This isn’t just about cutting expenses; it’s about understanding where your money goes and making conscious decisions. Inflation affects different categories of goods and services unevenly, so pay close attention to areas like food, utilities, transportation, and particularly healthcare, which often see higher price increases. By carefully tracking and categorizing your expenditures, you can spot trends and adjust your spending habits before inflation significantly impacts your cash flow.
Smart Budgeting and Spending Tactics
- Track All Expenses: Use budgeting apps or spreadsheets to gain a clear picture of your spending patterns and identify potential areas for savings.
- Prioritize Needs vs. Wants: Differentiate between essential expenditures and discretionary spending, making informed choices about where to allocate your resources.
- Seek Value: Look for ways to get more for your money, whether through bulk purchases, loyalty programs, or comparing prices for services and goods.
- Review Subscriptions: Regularly audit recurring subscriptions and memberships, canceling those you no longer use or find value in.
- Plan for Healthcare Costs: Research Medicare options, consider supplemental insurance, and factor in out-of-pocket expenses, as healthcare inflation is often higher.
Beyond day-to-day expenses, consider larger financial commitments. Can you pay off high-interest debts before retirement? Reducing debt obligations lessens the impact of rising interest rates and frees up more of your income for essential spending. Moreover, exploring ways to reduce fixed costs, such as downsizing your home or relocating to a lower cost-of-living area, can significantly enhance your financial resilience against inflation. These larger adjustments can provide a lasting buffer.
Ultimately, optimizing your spending and budgeting is about taking control of your financial narrative. It empowers you to live within your means, even as inflation chips away at purchasing power. By being mindful and strategic with your money, you can mitigate the effects of a 3.5% inflation rate and ensure your 2026 retirement savings can support the lifestyle you envision.
The Role of Professional Financial Advice in Inflation Management
Navigating the complexities of inflation and its potential impact on your 2026 retirement savings can be daunting. This is where the expertise of a qualified financial advisor becomes invaluable. A professional can offer personalized guidance, help you understand the nuances of various inflation-hedging strategies, and ensure your retirement plan is robust enough to withstand a 3.5% erosion. Their objective perspective can be the difference between a secure retirement and one fraught with financial anxieties.
Financial advisors can perform a comprehensive analysis of your current financial situation, risk tolerance, and retirement goals, factoring in realistic inflation projections. They can help you construct a diversified portfolio that aligns with your specific needs, recommending appropriate inflation-protected investments and income strategies. Moreover, they can assist with tax planning, which is another critical component of maximizing your real returns in an inflationary environment. Their role extends beyond simple investment recommendations; they provide a holistic financial roadmap.
Benefits of Consulting a Financial Advisor
- Personalized Strategy: Advisors create tailored plans based on your unique financial situation, risk tolerance, and retirement goals.
- Inflation-Adjusted Projections: They can model various inflation scenarios to show how a 3.5% erosion specifically impacts your future purchasing power.
- Access to Specialized Investments: Advisors may introduce you to less common inflation-hedging instruments or strategies.
- Behavioral Coaching: They help you avoid emotional investment decisions during volatile market or inflationary periods.
- Regular Review and Adjustment: An advisor ensures your plan is periodically reviewed and adjusted to stay relevant with changing economic conditions and personal circumstances.
When choosing a financial advisor, look for someone who is a fiduciary, meaning they are legally obligated to act in your best interest. Inquire about their experience with inflation-focused planning and their approach to retirement income strategies. A good advisor will educate you, empowering you to make informed decisions rather than simply dictating choices. They should be transparent about fees and their service model, ensuring you understand the value they bring.
In conclusion, while self-management of your finances is commendable, the complexities introduced by inflation, especially when nearing retirement, often warrant professional assistance. A financial advisor can provide the expertise, tools, and personalized strategies necessary to effectively combat the impact of inflation on your 2026 retirement savings, offering peace of mind and a clearer path to financial security.
Long-Term Perspective: Adapting Your Retirement Plan Beyond 2026
While the focus on the impact of inflation on your 2026 retirement savings is immediate, a truly effective strategy extends far beyond that specific year. Inflation is a persistent economic force, and your retirement plan must be designed with a long-term perspective, adaptable to changing economic conditions and potential future inflationary pressures. Thinking beyond the initial retirement date ensures your financial security for the entirety of your golden years.
Your retirement plan should not be a static document but a living strategy that evolves with time. Regular reviews, at least annually, are essential to assess how your investments are performing against inflation, whether your spending habits have changed, and if your overall financial goals remain on track. This ongoing vigilance allows for timely adjustments, preventing minor erosions from becoming significant threats to your financial well-being. The strategies you implement today for 2026 will lay the groundwork for a flexible and resilient plan for decades to come.
Building a Flexible and Adaptive Retirement Plan
- Annual Financial Reviews: Schedule regular check-ups with your financial advisor to review portfolio performance, spending, and inflation outlook.
- Stress Testing: Periodically run scenarios to see how your portfolio would fare under different inflation rates or market downturns.
- Contingency Funds: Maintain an emergency fund specifically for unexpected expenses or prolonged periods of high inflation.
- Continuous Learning: Stay informed about economic trends and financial strategies that can help combat inflation.
- Estate Planning Integration: Ensure your estate plan considers inflationary effects on asset values and beneficiary inheritances.
Consider the potential for your needs to change over a long retirement. Healthcare costs, for instance, tend to accelerate with age. Your plan should incorporate mechanisms to address these growing expenses, perhaps through dedicated health savings accounts (HSAs) or long-term care insurance. Flexibility also means being open to adjusting your spending or even considering part-time work in retirement if economic conditions necessitate it. The goal is to build a plan that can bend without breaking.
In conclusion, while preparing for 2026 is critical, the true test of your retirement plan’s strength lies in its long-term adaptability. By adopting a dynamic approach, regularly reviewing your strategy, and staying informed, you can ensure your retirement savings remain robust and capable of supporting your desired lifestyle, effectively mitigating the ongoing impact of inflation for years to come.
| Key Point | Brief Description |
|---|---|
| Inflation Impact | A 3.5% inflation rate significantly erodes retirement savings’ purchasing power over time. |
| Portfolio Assessment | Evaluate current assets for inflation resilience, focusing on real returns and future expenses. |
| Diversification & Hedges | Diversify across stocks, real estate, commodities, and TIPS to protect against inflation. |
| Professional Advice | Consult a financial advisor for personalized strategies and comprehensive inflation management. |
Frequently Asked Questions About Inflation and Retirement
What exactly is inflation and why does it matter for my retirement?▼
Inflation is the rate at which the general level of prices for goods and services is rising, and consequently, the purchasing power of currency is falling. For retirement, it means your savings will buy less in the future, eroding your financial security if not properly addressed.
How does a 3.5% inflation rate specifically affect my 2026 retirement?▼
A 3.5% inflation rate means that annually, your money loses 3.5% of its purchasing power. By 2026, the cumulative effect can significantly reduce the real value of your savings, requiring more capital to maintain the same lifestyle you planned for today.
What are the best investments to protect against inflation?▼
Effective inflation-hedging investments include Treasury Inflation-Protected Securities (TIPS), Series I Savings Bonds, real estate (via direct ownership or REITs), and certain commodities. A diversified portfolio combining these can offer robust protection.
Should I adjust my spending habits due to inflation now, before 2026?▼
Yes, absolutely. Optimizing your spending and budgeting now helps you build resilient financial habits. Identifying and reducing unnecessary expenses creates a buffer against rising costs, ensuring more of your savings can be invested to outpace inflation.
When should I seek professional financial advice regarding inflation?▼
It’s advisable to seek professional financial advice as soon as you recognize inflation as a threat, especially when nearing retirement. An advisor can provide personalized strategies, portfolio adjustments, and long-term planning to safeguard your retirement savings effectively.
Conclusion
The prospect of retiring in 2026 comes with both excitement and financial considerations, chief among them being the impact of inflation. As we’ve explored, a 3.5% erosion rate can subtly yet significantly diminish the purchasing power of your hard-earned retirement savings. However, this challenge is not insurmountable. By understanding the mechanisms of inflation, assessing your current portfolio’s resilience, strategically diversifying your investments with inflation-protected assets, optimizing your spending habits, and seeking professional guidance, you can build a robust defense for your financial future. The key lies in proactive planning and continuous adaptation, ensuring your golden years are truly secure and comfortable, free from the silent threat of eroded wealth.