2026 Federal Student Loan Interest Rates: A Comprehensive Guide
Advertisements
Understanding the 2026 federal student loan interest rates, fixed between 5.5% and 8.0%, is crucial for students and borrowers navigating their educational financing options and long-term financial commitments.
The landscape of higher education finance is constantly evolving, and staying informed about the latest changes is paramount for current and prospective students. For 2026, the latest 2026 federal student loan interest rates: a breakdown of fixed rates ranging from 5.5% to 8.0% presents a critical point of focus for anyone considering federal aid. These rates, set by Congress, directly influence the total cost of your education and your financial obligations post-graduation.
Understanding the Federal Student Loan System in 2026
The federal student loan system is a cornerstone of financial aid in the United States, designed to make higher education accessible to millions. These loans come with distinct advantages over private loans, primarily due to their fixed interest rates and various borrower protections. As we look towards 2026, understanding the structure and nuances of these federal programs becomes increasingly important for effective financial planning.
Federal student loans are typically offered through the U.S. Department of Education and include several types, each with specific eligibility criteria and loan limits. The fixed interest rates for 2026, ranging from 5.5% to 8.0%, are determined annually by Congress based on the 10-year Treasury note auction results. This ensures a predictable borrowing cost for students, safeguarding them from market volatility.
Types of Federal Student Loans and Their Rates
There are primarily three types of federal student loans available to students and parents, each carrying its own set of rules and interest rates. Understanding the differences is key to making informed borrowing decisions.
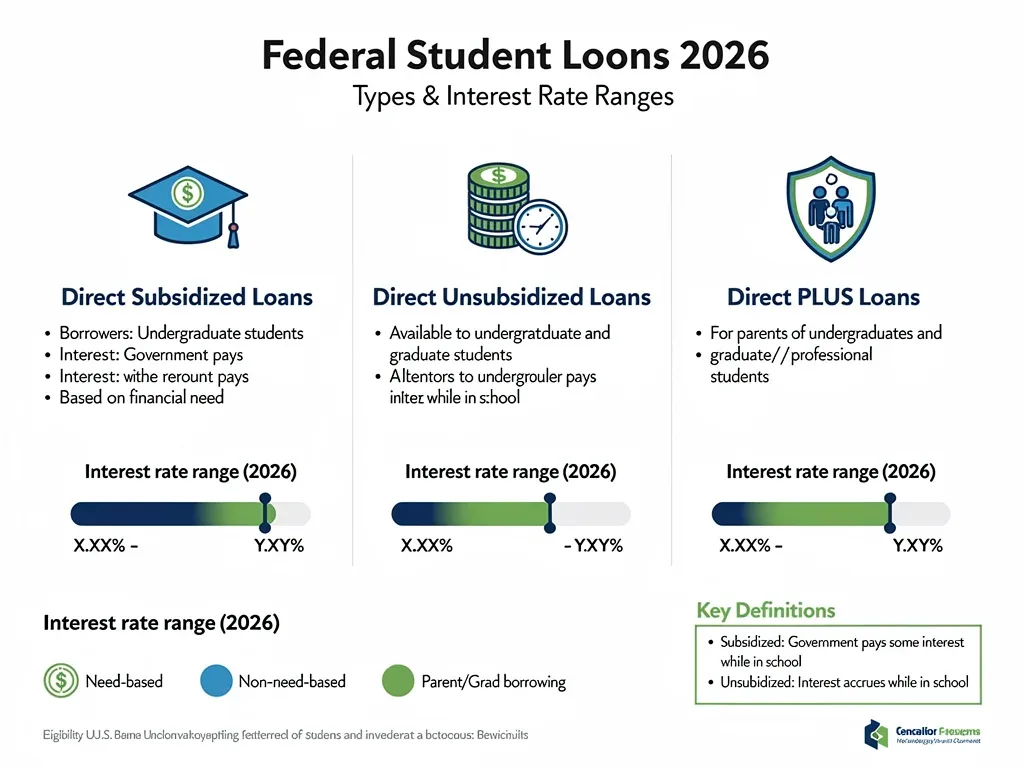
- Direct Subsidized Loans: These are for undergraduate students with demonstrated financial need. The government pays the interest while the student is in school at least half-time, during the grace period, and during deferment periods. For 2026, these loans will likely fall on the lower end of the 5.5% to 8.0% range.
- Direct Unsubsidized Loans: Available to both undergraduate and graduate students, regardless of financial need. Interest accrues from the moment the loan is disbursed, even while the student is in school. These rates are typically slightly higher than subsidized loans within the established range.
- Direct PLUS Loans: Offered to graduate or professional students (Grad PLUS) and parents of dependent undergraduate students (Parent PLUS). These loans require a credit check and generally carry the highest interest rates within the federal loan spectrum, often closer to the 8.0% mark for 2026.
Each loan type serves a different purpose, and the interest rates reflect the level of risk and government subsidy associated with them. Borrowers should prioritize subsidized loans first, followed by unsubsidized loans, and consider PLUS loans only after exhausting other options, due to their higher rates and credit requirements.
In conclusion, the federal student loan system provides crucial financial support for higher education. By understanding the various loan types and their associated fixed interest rates for 2026, borrowers can strategically plan their financing and minimize long-term debt burdens, ensuring a more stable financial future.
Factors Influencing 2026 Federal Student Loan Interest Rates
The determination of federal student loan interest rates is not arbitrary; it’s a carefully calculated process influenced by several economic and legislative factors. For 2026, the fixed rates ranging from 5.5% to 8.0% are a direct result of these complex interactions, reflecting the broader economic climate and congressional policy decisions. Understanding these underlying factors provides valuable insight into why rates are set at their current levels.
Primarily, federal student loan interest rates are tied to the 10-year Treasury note auction. This benchmark is considered a reliable indicator of the government’s borrowing costs. When the yield on the 10-year Treasury note rises, federal student loan interest rates typically follow suit. Conversely, a decrease in the Treasury yield can lead to lower student loan rates.
The Role of Congress and Economic Conditions
While the Treasury yield provides the baseline, Congress ultimately sets the formulas and caps for federal student loan interest rates. Each year, legislation is passed to establish the rates for new loans disbursed during a specific period. This legislative involvement means that political considerations and policy priorities can also play a role in shaping the final rates.
- Economic Stability: A strong economy often leads to higher interest rates as the Federal Reserve might raise rates to curb inflation. Conversely, during economic downturns, rates might be kept lower to stimulate growth.
- Government Spending and Budget: The overall federal budget and government spending priorities can influence how much the government is willing to subsidize student loans, indirectly affecting the rates offered to borrowers.
- Inflation Expectations: Lenders and policymakers consider inflation when setting interest rates. Higher inflation expectations can lead to higher rates to ensure that the real return on loans remains positive over time.
These factors combine to create the specific rates that students encounter. The fixed nature of federal student loan rates, once set, provides a level of certainty for borrowers, protecting them from unexpected fluctuations throughout their repayment period.
In essence, the 2026 federal student loan interest rates are a product of both market forces, as reflected by Treasury yields, and legislative decisions. This dual influence ensures a balance between economic realities and policy objectives, aiming to provide stable and predictable financing for higher education while managing federal costs.
Impact of Fixed Rates (5.5% to 8.0%) on Borrowers
The announcement of latest 2026 federal student loan interest rates: a breakdown of fixed rates ranging from 5.5% to 8.0% carries significant implications for current and future borrowers. Fixed interest rates, while offering predictability, also mean that the initial rate you secure will remain constant throughout the life of your loan. This can be both a blessing and a challenge, depending on market conditions and your personal financial situation.
For borrowers, fixed rates provide peace of mind. Unlike variable rates, which can fluctuate with the market, a fixed rate ensures that your monthly payments for the principal and interest portion remain consistent. This stability allows for more accurate budgeting and long-term financial planning, removing the uncertainty that comes with fluctuating interest costs.
Budgeting and Repayment Strategies with Fixed Rates
Understanding the fixed nature of these rates is crucial when developing your repayment strategy. A rate between 5.5% and 8.0% will directly influence the total amount you pay over the life of the loan. Higher rates mean a larger portion of your monthly payment goes towards interest, increasing the overall cost of borrowing.
- Early Repayment: With fixed rates, paying more than the minimum monthly payment, especially early in the loan term, can significantly reduce the total interest paid and shorten the repayment period.
- Consolidation Considerations: While federal student loans are already fixed, borrowers might consider federal loan consolidation to simplify payments or access different repayment plans. However, consolidation can sometimes result in a weighted average interest rate, which might be slightly higher than individual loan rates.
- Income-Driven Repayment (IDR) Plans: Fixed rates still allow access to various IDR plans, which adjust monthly payments based on your income and family size. While IDR plans can offer financial relief, they can also extend the repayment period and potentially increase the total interest paid.
The predictability of fixed rates empowers borrowers to make informed decisions about their financial future. It allows them to calculate the exact cost of their loans and choose repayment strategies that align with their income and career goals, without the constant worry of rate increases.
In summary, the fixed rates for 2026 federal student loans offer stability and predictability, which are invaluable for long-term financial planning. Borrowers should leverage this certainty to strategize their repayment, potentially saving money and achieving financial freedom sooner.
Comparing Federal vs. Private Student Loan Rates for 2026
When considering financing higher education, students often weigh their options between federal and private student loans. For 2026, with federal student loan interest rates fixed between 5.5% and 8.0%, it becomes even more pertinent to understand how these compare to the rates offered by private lenders. The choice between these two types of loans can significantly impact a borrower’s financial well-being, both during and after their studies.
Federal student loans, as discussed, come with fixed rates and a suite of borrower protections, including income-driven repayment plans, deferment, forbearance, and potential loan forgiveness programs. These features are designed to provide a safety net for borrowers facing financial hardship.
Key Differences in Interest Rates and Terms
Private student loans, offered by banks, credit unions, and other financial institutions, often come with variable interest rates, though fixed-rate options are also available. These rates are typically based on the borrower’s creditworthiness and can be significantly higher or lower than federal rates, depending on individual credit scores and market conditions.
- Rate Variability: Private loans frequently offer variable rates, which can change over time, potentially leading to unpredictable monthly payments. While some private lenders offer fixed rates, they may require a strong credit history or a co-signer.
- Credit Requirements: Federal loans generally do not require a credit check for most undergraduate loans (except PLUS loans), making them accessible to a wider range of students. Private loans, however, are highly credit-dependent, often necessitating a co-signer for students with limited credit history.
- Borrower Protections: Private loans typically lack the comprehensive borrower protections found in federal loans. This means fewer options for deferment, forbearance, or income-driven repayment, which can be critical during periods of unemployment or financial distress.
For 2026, the fixed federal rates of 5.5% to 8.0% provide a clear benchmark. Students with excellent credit might find slightly lower rates from private lenders, but they must carefully weigh the trade-off in terms of borrower protections. Conversely, students with less-than-perfect credit will almost certainly find federal loans to be the more favorable option.
In essence, while private loans can sometimes offer competitive rates, especially for borrowers with strong credit, federal student loans often provide greater security and flexibility due to their fixed rates and robust borrower protections. It is almost always recommended to exhaust federal loan options before considering private alternatives.
Strategies for Managing Federal Student Loan Debt in 2026
Effectively managing federal student loan debt, especially with the 2026 fixed rates ranging from 5.5% to 8.0%, requires a proactive and informed approach. Beyond simply making monthly payments, borrowers have several strategies at their disposal to minimize costs, navigate financial challenges, and ultimately achieve debt freedom. Understanding these options is crucial for optimizing your repayment journey.
The first step in managing your federal student loans is to understand all your loan details: the principal amount, interest rate, and repayment start date. This foundational knowledge allows you to assess your total debt burden and choose the most suitable repayment plan.
Exploring Repayment Plans and Options
The U.S. Department of Education offers a variety of repayment plans designed to accommodate different financial situations. These plans can significantly impact your monthly payments and the total amount you pay over time.

- Standard Repayment Plan: This plan typically has fixed monthly payments over a 10-year period. It generally results in the lowest total interest paid compared to other plans, making it ideal for those who can afford the payments.
- Graduated Repayment Plan: Payments start low and increase every two years, usually over a 10-year period. This can be beneficial for borrowers who expect their income to grow over time.
- Extended Repayment Plan: Offers lower monthly payments over a longer period (up to 25 years). This plan is suitable for borrowers with higher loan balances who need to reduce their monthly payment amount.
- Income-Driven Repayment (IDR) Plans: These plans cap your monthly payments at an affordable percentage of your discretionary income. After a certain number of years (20 or 25, depending on the plan) and if certain conditions are met, any remaining balance may be forgiven.
Beyond choosing a repayment plan, borrowers can also explore options like deferment and forbearance during periods of financial hardship. These temporary measures allow you to postpone payments, though interest may continue to accrue, especially on unsubsidized loans. Public Service Loan Forgiveness (PSLF) is another significant program for those working in eligible public service jobs.
In conclusion, managing federal student loan debt effectively involves more than just making payments. By thoroughly understanding the available repayment plans, exploring options for financial relief, and potentially pursuing forgiveness programs, borrowers can navigate their debt with greater confidence and work towards a more secure financial future.
Future Outlook and Potential Changes to Federal Loan Rates
While the latest 2026 federal student loan interest rates: a breakdown of fixed rates ranging from 5.5% to 8.0% provide a clear picture for the immediate future, the landscape of federal student loan policy is always subject to change. Understanding the factors that could influence future rates and policies is essential for long-term financial planning and advocacy. The political climate, economic forecasts, and ongoing discussions around higher education funding all play a role in shaping what borrowers might expect beyond 2026.
Interest rates for federal student loans are set annually by Congress. This means that while the 2026 rates are fixed for loans disbursed in that period, future rates for 2027 and beyond will be re-evaluated. Economic indicators, such as inflation, the federal budget deficit, and the performance of the 10-year Treasury note, will continue to be primary drivers in these annual determinations.
Legislative Debates and Policy Reforms
The conversation around student loan debt is a persistent topic in national politics. Various proposals for student loan reform, including changes to interest rate setting mechanisms, expanded forgiveness programs, or even interest-free loan options, frequently emerge from legislative bodies. These debates could lead to significant shifts in how federal student loans are structured and priced.
- Economic Projections: If inflation remains high or the Federal Reserve continues to adjust its monetary policy, it could exert upward pressure on future interest rates. Conversely, a stable or declining economic outlook might lead to efforts to keep rates lower to support economic recovery.
- Political Will: The composition of Congress and the priorities of the executive branch will heavily influence any legislative changes to student loan programs. A political environment focused on affordability for higher education might push for lower rates or more generous repayment terms.
- Market Demand: The overall demand for federal student loans can also indirectly influence policy. High demand might encourage policymakers to maintain attractive rates, while sustained low demand could signal a need for more competitive offerings.
Borrowers should remain vigilant about legislative updates and economic forecasts. Subscribing to official Department of Education communications and reputable financial news sources can help you stay informed about potential changes that could affect your loans.
In conclusion, while the 2026 rates are set, the future of federal student loan interest rates and policies remains dynamic. By staying informed about economic trends and legislative discussions, borrowers can better anticipate and adapt to potential changes, ensuring they are well-prepared for their ongoing financial commitments.
Optimizing Your Borrowing Decisions with 2026 Rates
Making informed borrowing decisions is perhaps the most critical step in managing student loan debt, especially with the latest 2026 federal student loan interest rates: a breakdown of fixed rates ranging from 5.5% to 8.0%. Every dollar borrowed and every percentage point of interest accumulated contributes to your long-term financial burden. Therefore, a strategic approach to borrowing can significantly reduce your overall cost of education.
Before accepting any loans, it is imperative to calculate your true financial need. This involves subtracting any grants, scholarships, or savings from your total cost of attendance. Only borrow what is absolutely necessary, as every dollar you don’t borrow is a dollar you don’t have to repay with interest.
Prioritizing Loan Types and Minimizing Debt
Given the different interest rates and terms associated with various federal loan types, prioritizing which loans to accept first is a smart financial move. This strategy ensures you take advantage of the most favorable terms available to you.
- Maximize Grants and Scholarships: These are free money that does not need to be repaid. Apply for as many as you can, as they directly reduce your borrowing needs.
- Accept Subsidized Loans First: If you qualify, Direct Subsidized Loans offer the best terms, as the government pays the interest during certain periods. These will typically be at the lower end of the 5.5% to 8.0% range.
- Consider Unsubsidized Loans Next: These are a good option if you need additional funds, but be aware that interest accrues immediately.
- Limit PLUS Loans: Due to their higher interest rates and credit check requirements, Direct PLUS Loans should generally be considered a last resort after exhausting all other federal aid and personal savings.
Beyond prioritizing loan types, actively seeking ways to reduce your overall cost of attendance can also minimize your borrowing. This might include attending a community college for the first two years, living at home, or working part-time during your studies.
In conclusion, optimizing your borrowing decisions for 2026 federal student loans means being strategic and disciplined. By maximizing free aid, prioritizing the most advantageous loan types, and consciously minimizing the amount you borrow, you can significantly reduce your future debt burden and set yourself up for greater financial success.
| Key Aspect | Description for 2026 |
|---|---|
| Interest Rate Range | Fixed rates for new federal student loans range from 5.5% to 8.0%. |
| Loan Types Impacted | Direct Subsidized, Unsubsidized, and PLUS Loans are subject to these fixed rates. |
| Rate Determination | Rates are set annually by Congress, linked to the 10-year Treasury note auction. |
| Borrower Impact | Fixed rates offer predictable payments, aiding long-term financial planning and budgeting. |
Frequently Asked Questions About 2026 Federal Student Loan Rates
What are the specific interest rates for each federal loan type in 2026?▼While the overall range is 5.5% to 8.0%, specific rates vary by loan type. Direct Subsidized and Unsubsidized Loans for undergraduates typically have lower rates, while graduate and Parent PLUS loans are usually at the higher end of this spectrum. Exact rates are announced closer to the disbursement period.
How do these 2026 rates compare to previous years?▼Federal student loan interest rates fluctuate annually based on economic conditions and congressional action. These 2026 rates reflect the current economic environment and may be higher or lower than those in prior years, emphasizing the importance of staying informed each academic year.
Are these rates fixed or variable?▼All federal student loans, including those disbursed in 2026, come with fixed interest rates. This means the rate you receive at the time of disbursement will remain the same for the entire life of the loan, providing stability and predictable monthly payments for borrowers.
Can I get a lower interest rate on my federal student loans?▼Federal student loan interest rates are set by Congress and are generally non-negotiable. However, certain benefits like interest subsidies on Direct Subsidized Loans can effectively reduce your total cost. Consolidating federal loans can result in a weighted average rate, but typically doesn’t lower it significantly.
What happens if I cannot afford my federal student loan payments?▼Federal student loans offer several borrower protections, including income-driven repayment plans, deferment, and forbearance. These options can temporarily reduce or postpone your payments during times of financial hardship. Contact your loan servicer to discuss which options might be suitable for your situation.
Conclusion
The latest 2026 federal student loan interest rates: a breakdown of fixed rates ranging from 5.5% to 8.0% represents a crucial piece of financial information for anyone pursuing higher education in the United States. These fixed rates offer a degree of predictability that is invaluable for long-term financial planning, allowing students and their families to budget effectively and understand their repayment obligations from the outset. By understanding the types of federal loans available, the factors influencing these rates, and the various repayment strategies, borrowers can make informed decisions that minimize their debt burden and pave the way for a more secure financial future. Staying informed about potential policy changes and optimizing borrowing choices are key to navigating the complex world of student finance successfully.