Estate Planning 2026: Navigating the $13.61 Million Exemption
Advertisements
Understanding the $13.61 million federal estate tax exemption limit in 2026 is crucial for effective estate planning, allowing individuals to strategically manage assets and minimize tax liabilities for their beneficiaries.
As we approach 2026, the landscape of wealth transfer is evolving, making proactive estate planning in 2026: navigating the $13.61 million federal exemption limit more critical than ever. This guide will help you understand the nuances of the federal estate tax exemption and empower you to make informed decisions for your legacy.
Understanding the 2026 Federal Estate Tax Exemption
The federal estate tax exemption is a critical component of wealth transfer, directly impacting how much of an estate can pass to heirs free of federal estate taxes. For 2026, this exemption is projected to be a substantial $13.61 million per individual, a figure that demands attention from anyone with significant assets.
This exemption is not static; it adjusts annually for inflation. However, the current projection for 2026 is particularly noteworthy because it represents a significant threshold for many high-net-worth individuals and families. Understanding this number is the first step in formulating an effective estate plan that minimizes tax burdens and ensures your beneficiaries receive the maximum possible inheritance.
Historical context and future outlook
The federal estate tax exemption has seen considerable changes over the past decades, often influenced by legislative shifts and economic conditions. From much lower limits in earlier years to higher thresholds more recently, these changes underscore the dynamic nature of estate planning.
- Past fluctuations: The exemption has varied significantly, sometimes dropping sharply due to sunset provisions or legislative action.
- Current legislative environment: While the current exemption is generous, there is always potential for future legislative changes that could alter these limits.
- Impact on planning: Historical trends emphasize the need for flexible estate plans that can adapt to potential future policy shifts.
Looking ahead, the Tax Cuts and Jobs Act of 2017 (TCJA) significantly increased the exemption amount, but many of its provisions are set to expire at the end of 2025. This means that without new legislation, the exemption amount could revert to pre-TCJA levels, adjusted for inflation, potentially around half of the 2026 projected figure. This looming change makes 2026 a pivotal year for estate planning, as individuals must consider the possibility of a reduced exemption in subsequent years.
In conclusion, the $13.61 million federal estate tax exemption for 2026 provides a valuable window of opportunity for strategic planning. However, the potential for future legislative changes necessitates a proactive and adaptable approach to ensure long-term wealth preservation.
Strategic Gifting and the Annual Exclusion
Strategic gifting is a powerful tool within estate planning, allowing individuals to reduce the size of their taxable estate while providing financial support to loved ones. The annual gift tax exclusion is a key component of this strategy, permitting gifts up to a certain amount per recipient each year without incurring gift tax or using up any of your lifetime exemption.
For 2026, the annual gift tax exclusion is expected to be around $18,000 per recipient. This means you can give $18,000 to as many individuals as you wish each year, and those gifts will not count against your $13.61 million lifetime exemption. This strategy can be particularly effective for large families or individuals looking to make regular, smaller distributions over time.
Maximizing annual exclusion gifts
To maximize the benefits of the annual exclusion, consider several approaches. One common strategy is to make gifts early and consistently. The more years you utilize the exclusion, the more wealth you can transfer tax-free.
- Spousal gifting: Spouses can combine their annual exclusions, effectively doubling the tax-free gift amount to $36,000 per recipient per year.
- Direct payments: Payments made directly for medical expenses or educational tuition on behalf of another individual are exempt from gift tax and do not count against the annual exclusion or lifetime exemption.
- Crummey trusts: For gifts to trusts, especially for minors, a Crummey trust allows beneficiaries to withdraw the gifted funds for a limited period, making the gift qualify for the annual exclusion.
Another important aspect is understanding the difference between annual exclusion gifts and gifts that utilize your lifetime exemption. While annual exclusion gifts are relatively small, they accumulate over time and can significantly reduce the value of your taxable estate. Gifts exceeding the annual exclusion amount will begin to chip away at your $13.61 million lifetime exemption. It’s crucial to keep meticulous records of all gifts made to accurately track your remaining exemption.
In summary, strategic gifting, particularly through the annual exclusion, offers a practical and effective method to reduce your taxable estate. By understanding and consistently applying these rules, you can significantly enhance your estate planning efforts for 2026 and beyond.
The Role of Trusts in Estate Planning for High-Net-Worth Individuals
For individuals with substantial assets exceeding the federal exemption limit, trusts become an indispensable tool in estate planning. Trusts offer a sophisticated way to manage and distribute assets, providing control, privacy, and significant tax advantages that go beyond what a simple will can offer. They are particularly valuable for high-net-worth individuals aiming to protect their wealth across generations.
A trust involves three parties: the grantor (who creates the trust), the trustee (who manages the assets), and the beneficiaries (who receive the assets). By transferring assets into a trust, the grantor can dictate how and when those assets are distributed, potentially avoiding probate and reducing estate taxes. The flexibility of trusts allows for highly customized plans that address specific family needs and financial goals.
Types of trusts and their benefits
The world of trusts is diverse, with each type serving a unique purpose. Choosing the right trust depends on your specific objectives, whether it’s minimizing taxes, protecting assets, or providing for dependents with special needs.
- Irrevocable trusts: Once assets are placed in an irrevocable trust, they are generally removed from the grantor’s estate, thereby reducing the taxable estate. This type of trust offers significant estate tax savings and asset protection from creditors.
- Revocable living trusts: While assets in a revocable trust are still part of the grantor’s taxable estate, these trusts are excellent for avoiding probate, maintaining privacy, and providing for seamless asset management during incapacitation.
- Grantor retained annuity trusts (GRATs): GRATs allow grantors to transfer appreciating assets out of their estate with minimal gift tax implications, especially effective in low-interest-rate environments.
- Charitable trusts: These trusts combine philanthropic goals with estate planning benefits, offering tax deductions and reducing the taxable estate while supporting charitable causes.
The strategic use of trusts can also help navigate the generation-skipping transfer (GST) tax, which applies to transfers to beneficiaries two or more generations younger than the grantor. By carefully structuring trusts, it’s possible to minimize or even eliminate this tax, ensuring more wealth reaches your intended heirs.
Ultimately, trusts are a cornerstone of advanced estate planning, offering unparalleled control and tax efficiency. Consulting with an experienced estate attorney is crucial to determine the most suitable trust structures for your individual circumstances and to ensure proper implementation.
Portability and Maximizing Spousal Exemptions
Portability is a crucial concept in federal estate tax law that allows a surviving spouse to utilize any unused portion of their deceased spouse’s federal estate tax exemption. This provision, enacted in 2010, significantly changed estate planning for married couples, offering a mechanism to maximize the total amount of wealth that can pass to heirs free of federal estate taxes.
Before portability, if the first spouse to die did not fully use their estate tax exemption, that unused portion was lost. With portability, the surviving spouse can add the deceased spouse’s unused exemption (DSUE) amount to their own exemption. For 2026, this means a married couple could potentially pass on up to $27.22 million ($13.61 million per spouse) free of federal estate tax, provided the DSUE is properly claimed.
Claiming the deceased spouse’s unused exemption (DSUE)
To claim the DSUE, the executor of the deceased spouse’s estate must file a federal estate tax return (Form 706), even if no estate tax is due. This election must be made timely, typically within nine months of the deceased spouse’s death, though extensions are sometimes available.
- Timely filing: The Form 706 must be filed within the specified period to make the portability election valid.
- IRS requirements: Adhering to all IRS guidelines for reporting the estate’s value and making the election is critical.
- Professional guidance: Given the complexities, working with an experienced estate attorney or tax professional is highly recommended to ensure the election is correctly made.
While portability offers substantial benefits, it’s not a one-size-fits-all solution. There are situations where traditional trust structures, such as bypass trusts (also known as credit shelter trusts), might still be more advantageous. For instance, bypass trusts can protect assets from creditors and future spouses of the survivor, and they can also grow outside of the surviving spouse’s estate, potentially shielding more wealth from future estate taxes.
Ultimately, understanding and properly utilizing portability is a cornerstone of modern estate planning for married couples. It provides a powerful mechanism to double the effective estate tax exemption, but careful consideration of individual circumstances and professional advice are essential to determine the best approach for maximizing wealth transfer.
The Sunset of TCJA Provisions and Future Implications
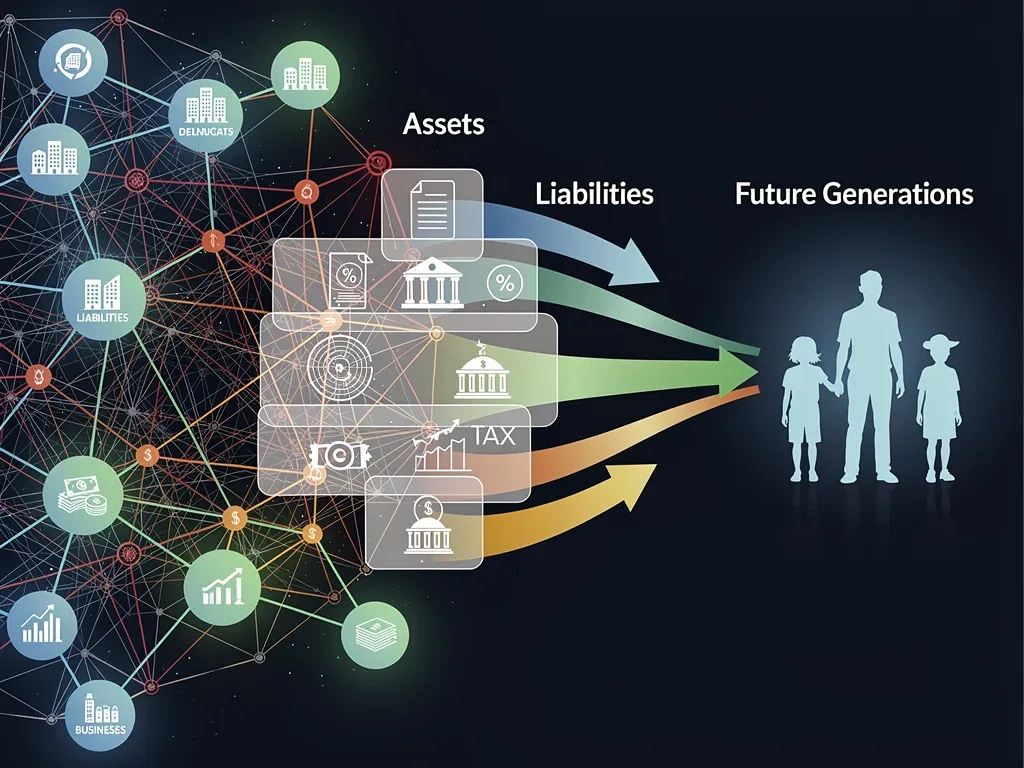
The Tax Cuts and Jobs Act of 2017 (TCJA) brought about significant changes to the federal estate and gift tax landscape, most notably by substantially increasing the exemption amounts. However, a critical aspect of the TCJA is that many of its provisions are temporary, specifically set to expire at the end of 2025. This sunset provision has profound implications for estate planning in 2026 and beyond, as the federal exemption limit is projected to revert to a much lower figure.
Without new legislation, the federal estate tax exemption in 2026 is expected to drop from the projected $13.61 million to approximately half that amount, around $7 million per individual (adjusted for inflation from the 2011 baseline). This potential reduction means that many more estates could become subject to federal estate tax, necessitating a re-evaluation of existing estate plans for a wider range of individuals.
Planning for a reduced exemption
The impending reduction in the exemption amount presents both challenges and opportunities. For those with estates currently below the 2026 exemption but potentially above the post-sunset exemption, proactive planning is essential. Strategies that might not have been necessary before could become critical to minimize future tax liabilities.
- Accelerated gifting: Consider making larger gifts before the end of 2025 to utilize the higher exemption amounts while they are still available. The IRS has confirmed that gifts made under the higher exemption will not be clawed back if the exemption decreases.
- Revisiting trust structures: Existing trusts might need to be reviewed and potentially modified to account for the reduced exemption. New trust strategies, such as spousal lifetime access trusts (SLATs), could become more appealing.
- Life insurance strategies: Life insurance policies held in irrevocable life insurance trusts (ILITs) can provide liquidity to cover potential estate taxes, becoming even more valuable with a lower exemption.
The uncertainty surrounding future legislation also adds a layer of complexity. While the current sunset is scheduled, Congress could pass new laws that alter the exemption amount again, either extending the higher limits or implementing new rules. This dynamic environment underscores the importance of staying informed and maintaining flexibility in your estate plan.
In conclusion, the sunset of the TCJA provisions is a significant factor in estate planning in 2026: navigating the $13.61 million federal exemption limit. Preparing for a potentially reduced exemption is paramount, requiring careful consideration of gifting strategies, trust modifications, and continuous monitoring of legislative developments.
Advanced Estate Planning Techniques
Beyond the fundamental strategies of wills, trusts, and gifting, advanced estate planning techniques offer sophisticated solutions for individuals with highly complex financial situations or those aiming for specific long-term goals. These techniques often involve intricate legal and financial structures designed to optimize tax efficiency, protect assets, and ensure a lasting legacy.
One such technique is the use of family limited partnerships (FLPs) or family limited liability companies (FLLCs). These entities allow individuals to transfer assets, such as real estate or business interests, to family members while retaining some control and often benefiting from valuation discounts for gift and estate tax purposes. The discounts arise because the transferred interests are typically non-controlling and lack marketability, reducing their taxable value.
Implementing sophisticated strategies
Implementing advanced estate planning techniques requires a deep understanding of tax law and a precise execution plan. These strategies are not suitable for everyone and typically involve significant legal and administrative costs, but the potential benefits for large estates can be substantial.
- GRATs (Grantor Retained Annuity Trusts): As mentioned earlier, GRATs are particularly effective for transferring appreciating assets out of an estate with minimal gift tax liability, especially in a low-interest-rate environment.
- QPRTs (Qualified Personal Residence Trusts): A QPRT allows you to transfer your primary or secondary residence to beneficiaries at a reduced gift tax value while retaining the right to live in it for a specified term. After the term, the residence passes to your beneficiaries outside of your taxable estate.
- IDGTs (Intentionally Defective Grantor Trusts): IDGTs are designed to remove assets and their future appreciation from your taxable estate for estate tax purposes, while you, as the grantor, remain responsible for income taxes on the trust’s income. This allows the trust assets to grow income-tax-free for the beneficiaries.
Another powerful technique involves charitable lead trusts (CLTs) and charitable remainder trusts (CRTs). These trusts combine philanthropic giving with estate planning goals. A CLT provides an income stream to a charity for a period, with the remainder passing to non-charitable beneficiaries, often at a reduced gift or estate tax cost. A CRT, conversely, provides an income stream to non-charitable beneficiaries for a period, with the remainder going to charity.
These advanced techniques require careful consideration of your financial situation, family dynamics, and long-term objectives. Engaging a team of experienced professionals, including estate attorneys, financial advisors, and tax specialists, is essential to design and implement these complex strategies effectively and compliantly.
The Importance of Regular Review and Professional Guidance
Estate planning is not a one-time event but an ongoing process that requires regular review and adaptation. The legal, financial, and personal landscapes are constantly changing, and an estate plan that was perfect a few years ago might be outdated or ineffective today. This is particularly true given the dynamic nature of tax laws, such as the potential sunset of TCJA provisions at the end of 2025 and the projected $13.61 million federal exemption limit for 2026.
Life events also play a significant role in necessitating estate plan reviews. Marriages, divorces, births of children or grandchildren, deaths of beneficiaries or executors, significant changes in asset values, or the acquisition of new properties all warrant a re-evaluation of your existing plan. Without regular updates, your estate plan might not reflect your current wishes or could lead to unintended consequences for your heirs.
When and why to review your estate plan
A comprehensive review of your estate plan should ideally occur every three to five years, or immediately following any significant life event. This proactive approach ensures that your plan remains aligned with your goals and takes advantage of current laws and exemptions.
- Changes in tax laws: Legislative changes, like the TCJA sunset, can dramatically alter the tax implications of your estate.
- Fluctuations in asset values: A substantial increase or decrease in your net worth can impact the effectiveness of your existing plan.
- Family dynamics: Births, deaths, marriages, or divorces within your family often require adjustments to beneficiary designations and guardianship provisions.
- Changes in health or capacity: Updates to powers of attorney and healthcare directives become crucial as health situations evolve.
Engaging experienced professionals is paramount throughout this process. An estate planning attorney can ensure your documents are legally sound and compliant with current laws. A financial advisor can help you align your investment strategies with your estate goals, while a tax advisor can identify opportunities to minimize tax liabilities. These professionals work collaboratively to create a holistic plan that addresses all facets of your financial and personal wishes.
In conclusion, the efficacy of your estate plan hinges on its ability to adapt to changing circumstances. Regular reviews and the invaluable guidance of a team of experts are essential to ensure your legacy is protected, your wishes are honored, and your beneficiaries are provided for efficiently and effectively, especially when navigating the complexities of estate planning in 2026: navigating the $13.61 million federal exemption limit.
| Key Point | Brief Description |
|---|---|
| 2026 Federal Exemption | Projected $13.61 million per individual, crucial for tax-free wealth transfer. |
| TCJA Sunset Impact | Exemption may halve post-2025, necessitating urgent planning. |
| Portability for Spouses | Allows surviving spouse to use deceased spouse’s unused exemption. |
| Trusts & Gifting | Key tools for tax reduction and controlled asset distribution. |
Frequently Asked Questions About 2026 Estate Planning
What is the federal estate tax exemption limit for 2026?▼The federal estate tax exemption limit for 2026 is projected to be $13.61 million per individual. This amount is adjusted annually for inflation and dictates how much of an estate can pass to heirs without federal estate tax.
How will the sunset of TCJA provisions affect estate planning?▼Without new legislation, the exemption limit is expected to revert to approximately $7 million per individual after 2025. This means more estates could become subject to federal estate tax, requiring urgent review of existing plans.
What is portability in estate tax and how does it work?▼Portability allows a surviving spouse to use any unused portion of their deceased spouse’s federal estate tax exemption. This can effectively double the exemption for married couples, potentially reaching $27.22 million in 2026.
Are trusts still important with such a high exemption limit?▼Yes, trusts remain crucial for high-net-worth individuals. They offer benefits like probate avoidance, asset protection from creditors, privacy, and specialized distribution instructions, even if estate tax is not a primary concern.
How often should I review my estate plan?▼It’s recommended to review your estate plan every three to five years, or immediately after significant life events such as marriage, divorce, birth of a child, death of a beneficiary, or substantial changes in your financial assets or tax laws.
Conclusion
The landscape of estate planning in 2026: navigating the $13.61 million federal exemption limit is characterized by both significant opportunities and impending changes. The generous federal estate tax exemption offers a valuable window for wealth transfer, but the looming sunset of TCJA provisions underscores the critical need for proactive and adaptable planning. Strategic gifting, the judicious use of various trust structures, and the understanding of portability provisions are not just theoretical concepts; they are practical tools that, when expertly applied, can safeguard your legacy and ensure your beneficiaries receive your intended inheritance with minimal tax erosion. Ultimately, comprehensive estate planning is an ongoing commitment, demanding regular review and the invaluable guidance of experienced legal and financial professionals to navigate its complexities effectively and secure your financial future for generations to come.