Student Loan Forgiveness 2026: Updates & 10% More Qualification
Advertisements
Student loan forgiveness in 2026 continues to evolve with new programs and adjusted criteria, offering borrowers critical opportunities for relief, including pathways to qualify for an additional 10% in debt cancellation.
Navigating the complex world of student loan debt can be daunting, but understanding the latest developments in student loan forgiveness 2026 offers a beacon of hope for many. As policies shift and new initiatives emerge, staying informed is crucial for borrowers seeking relief. This comprehensive guide will explore the most recent updates, detail eligibility requirements, and even reveal strategies to potentially qualify for an additional 10% in loan forgiveness.
Understanding the Evolving Landscape of Student Loan Forgiveness
The landscape of student loan forgiveness has been a dynamic one, marked by significant policy changes and ongoing discussions. For borrowers looking towards 2026, it is essential to recognize that federal programs remain the primary avenues for relief, though their structures and benefits can be subject to adjustments. These programs aim to alleviate the burden of student debt for specific groups of borrowers or those who meet certain criteria, often tied to public service or financial hardship.
Recent years have seen various temporary measures and permanent reforms, illustrating a commitment to addressing the national student debt crisis. While some initiatives may have sunsetted, others have been strengthened or refined. The focus for 2026 is largely on the continued implementation and potential expansion of existing frameworks, alongside any new legislative proposals that might gain traction. Keeping abreast of these changes is paramount to understanding your options.
Key Federal Forgiveness Programs
Several federal programs form the backbone of student loan forgiveness. These programs each have distinct requirements and benefits, designed to cater to different borrower circumstances. Understanding the nuances of each is the first step toward determining your eligibility. The most prominent among these include Public Service Loan Forgiveness (PSLF) and various Income-Driven Repayment (IDR) plans.
- Public Service Loan Forgiveness (PSLF): Designed for individuals working full-time for qualifying non-profit organizations or government agencies, PSLF forgives the remaining balance on Direct Loans after 120 qualifying monthly payments.
- Income-Driven Repayment (IDR) Plans: These plans adjust your monthly payment based on your income and family size. After 20 or 25 years (depending on the plan and loan type) of qualifying payments, any remaining balance is forgiven.
- Teacher Loan Forgiveness: Offers up to $17,500 in forgiveness for eligible teachers who work for five consecutive years in low-income schools or educational service agencies.
Each of these programs has specific stipulations regarding loan types, employment, and payment history. It is vital to confirm that your loans are federal Direct Loans, as private loans are generally not eligible for federal forgiveness programs. The criteria for what constitutes a ‘qualifying payment’ or ‘qualifying employment’ can also be precise, requiring careful attention to detail.
The evolving nature of these programs means that what was true last year might have slight modifications for 2026. Therefore, regularly checking official Department of Education resources and your loan servicer’s information is a prudent practice. These updates can sometimes include temporary waivers or expansions of eligibility that could significantly impact your path to forgiveness.
Eligibility Requirements: Who Qualifies for Forgiveness in 2026?
Determining eligibility for student loan forgiveness in 2026 involves a detailed review of several factors, primarily focusing on your loan types, employment history (for some programs), and repayment behavior. Not all student loans are created equal when it comes to forgiveness, and understanding these distinctions is your starting point. Generally, federal student loans, particularly Direct Loans, are the ones that qualify for the most robust forgiveness options.
Private student loans, issued by banks or other private lenders, are almost universally excluded from federal forgiveness programs. This distinction is critical and often a source of confusion for borrowers. If you have private loans, you will need to explore alternative relief options, such as refinancing or private lender hardship programs, which operate outside the scope of federal forgiveness.
Loan Types and Consolidation
For federal loans, the type of loan you hold plays a significant role in your eligibility. Federal Family Education Loans (FFEL) and Perkins Loans, for example, often need to be consolidated into a Direct Consolidation Loan to become eligible for programs like PSLF or certain IDR plans. This consolidation process can sometimes reset your payment count for forgiveness, so it is crucial to understand the implications before proceeding.
- Direct Loans: The most straightforward path to forgiveness, as these are directly eligible for PSLF and all IDR plans.
- FFEL and Perkins Loans: May require consolidation into a Direct Loan to qualify for federal forgiveness programs.
- Private Loans: Generally not eligible for federal forgiveness; explore private relief options.
Understanding your loan portfolio is the first step. You can typically find this information by logging into your account on StudentAid.gov. This portal provides a comprehensive overview of your federal student loans, including their types, balances, and current repayment status.
Beyond loan type, your employment status and repayment history are paramount. For PSLF, consistent full-time employment with a qualifying employer is non-negotiable. For IDR plans, your income and family size are continuously assessed to determine your monthly payment and, ultimately, your forgiveness timeline. Any changes in these factors can affect your eligibility or the amount of time until forgiveness.
The Public Service Loan Forgiveness (PSLF) Program in 2026
The Public Service Loan Forgiveness (PSLF) program continues to be a cornerstone of federal student loan relief, particularly for those dedicated to public service. In 2026, the core tenets of PSLF remain consistent: working full-time for a qualifying employer and making 120 qualifying monthly payments. However, understanding the specifics of what constitutes ‘qualifying’ is crucial for successful application.
Qualifying employment includes government organizations at any level (federal, state, local, or tribal), 501(c)(3) non-profit organizations, and other non-profit organizations that provide specific public services. It is important to note that certain types of non-profits, such as those primarily engaged in partisan political activity or religious instruction, typically do not qualify. Regularly submitting the PSLF Employment Certification Form is highly recommended to ensure your employment is on track and your payments are being counted correctly.
Ensuring Qualifying Employment and Payments
For PSLF, ‘full-time’ generally means working at least 30 hours per week for one or more qualifying employers. Payments must be made on Direct Loans, under a qualifying income-driven repayment plan, and on time. Payments made while loans are in deferment or forbearance (unless under specific temporary waivers) typically do not count towards the 120 required payments.
- Qualifying Employers: Government entities (federal, state, local, tribal) and 501(c)(3) non-profits.
- Full-Time Employment: Generally 30+ hours per week.
- Qualifying Payments: 120 on-time payments made under an IDR plan on Direct Loans.
The PSLF Help Tool on StudentAid.gov is an invaluable resource for borrowers to track their progress, identify qualifying employers, and submit their Employment Certification Forms. This tool helps streamline the process and provides a clear record of your journey towards forgiveness. Any discrepancies should be addressed promptly with your loan servicer.
While the PSLF program has faced scrutiny and adjustments over the years, its fundamental purpose remains intact. Borrowers who have committed to public service should diligently pursue this path, ensuring all criteria are met. The potential for full student loan forgiveness after 10 years of service can be life-changing, making careful planning and consistent record-keeping essential.
Income-Driven Repayment (IDR) Plans and Forgiveness in 2026
Income-Driven Repayment (IDR) plans offer a vital safety net for borrowers struggling with high monthly payments relative to their income. In 2026, these plans continue to be a primary pathway to eventual loan forgiveness, offering adjusted payments based on a borrower’s discretionary income. After a specified period of payments (typically 20 or 25 years), any remaining loan balance is forgiven, though this forgiven amount may be subject to federal income tax.
There are several IDR plans available, including Revised Pay As You Earn (REPAYE), Pay As You Earn (PAYE), Income-Based Repayment (IBR), and Income-Contingent Repayment (ICR). Each plan has slightly different formulas for calculating monthly payments and varying forgiveness timelines. Choosing the right IDR plan is a critical decision that can significantly impact your financial future and your path to forgiveness.
Choosing the Right IDR Plan and Maximizing Benefits
The optimal IDR plan depends on your specific financial situation, including your income, family size, and the types of federal loans you hold. For instance, PAYE and REPAYE often offer the lowest monthly payments for many borrowers, calculating payments based on 10% of discretionary income. IBR, on the other hand, calculates payments based on 10% or 15% of discretionary income, depending on when you took out your loans.
- REPAYE (Revised Pay As You Earn): Generally 10% of discretionary income; forgiveness after 20 years for undergraduate loans, 25 years for graduate loans.
- PAYE (Pay As You Earn): Generally 10% of discretionary income; forgiveness after 20 years.
- IBR (Income-Based Repayment): 10% or 15% of discretionary income; forgiveness after 20 or 25 years.
It is crucial to recertify your income and family size annually for your IDR plan. Failing to do so can result in your payments reverting to the standard 10-year plan amount, potentially increasing your monthly burden and delaying your progress toward forgiveness. Proactive management of your IDR plan is key to maximizing its benefits.
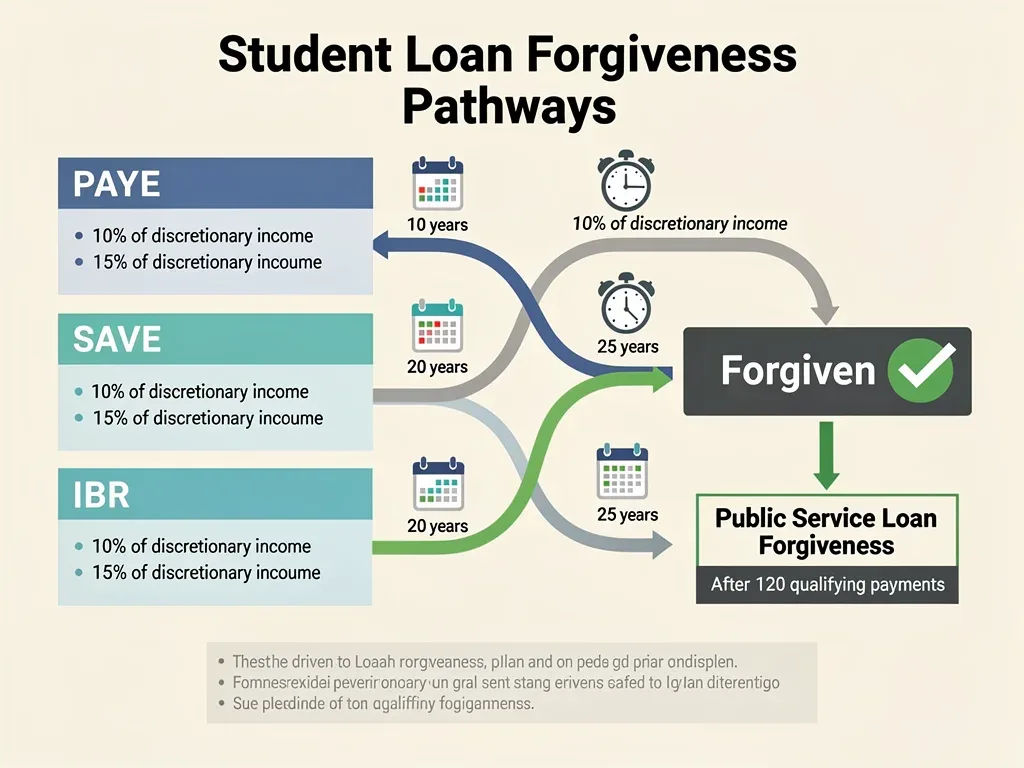
The SAVE plan (Saving on a Valuable Education), introduced recently, is also a significant development. It offers potentially lower monthly payments and more generous interest subsidies than previous IDR plans. Borrowers should investigate if the SAVE plan is the best option for their circumstances, as it could accelerate their path to forgiveness or significantly reduce their monthly costs.
Strategies to Qualify for 10% More Forgiveness
While the standard forgiveness programs offer substantial relief, some strategic approaches and specific circumstances can potentially lead to an additional 10% in loan forgiveness or a faster path to it. This often involves leveraging specific program rules, taking advantage of temporary waivers, or pursuing specific career paths that offer enhanced benefits. Staying informed about these less common, but highly impactful, opportunities is crucial.
One primary way to potentially gain additional benefits is through the intricacies of the SAVE plan. This plan has been designed to offer more favorable terms than older IDR plans, including a reduction in discretionary income calculation for payments and more generous interest subsidies. For some borrowers, this could equate to a significantly lower total amount paid over time, effectively providing a greater percentage of forgiveness.
Leveraging Specific Program Features and Waivers
The SAVE plan, for instance, calculates discretionary income differently, allowing a larger portion of income to be protected from monthly payment calculations. This translates to lower monthly payments for many borrowers. Furthermore, the plan includes a provision where if your calculated monthly payment doesn’t cover the monthly interest, the government covers the remaining interest, preventing your balance from growing. This interest subsidy can be a powerful tool in reducing the overall amount you owe and thus increasing the effective percentage of forgiveness.
- SAVE Plan Benefits: Lower discretionary income calculation, preventing interest capitalization.
- Temporary Waivers: Keep an eye out for any announced limited-time waivers that might count previously ineligible payments towards forgiveness.
- Targeted Professions: Certain professions, beyond general public service, might offer specific state or institutional forgiveness programs.
Historically, the Department of Education has occasionally offered temporary waivers, such as the PSLF Limited Waiver, which allowed past payments that would not have previously qualified to count toward PSLF. While these are not regular occurrences, staying vigilant for any future announcements could unlock significant additional forgiveness. These waivers often have strict deadlines and specific criteria, so prompt action is essential.
Additionally, some states or specific employers offer their own loan repayment assistance programs (LRAPs) for professionals in high-need areas, such as healthcare or education. These programs can sometimes be layered on top of federal forgiveness, effectively reducing your debt faster or covering a larger portion of it. Researching such local or institutional programs in your field is a worthwhile endeavor.
Application Process and Essential Documentation
The application process for student loan forgiveness can vary depending on the program, but it generally requires meticulous attention to detail and thorough documentation. Whether you are applying for PSLF or enrolling in an IDR plan, having all your financial and employment records in order is paramount. Rushing through the application or failing to provide accurate information can lead to delays or even denial of benefits.
For IDR plans, the application typically involves providing income information, usually through tax returns or pay stubs, and details about your family size. This information is used to calculate your monthly payment. For PSLF, the process is more involved, requiring regular certification of your employment and tracking of your qualifying payments. The PSLF Help Tool is designed to assist with this, but it is ultimately the borrower’s responsibility to ensure all forms are submitted correctly and on time.
Key Steps and Documents for a Smooth Application
Before you even begin the application, gather all relevant documents. This includes federal student loan statements, tax returns (federal and state), pay stubs, and employment verification letters. For PSLF, keeping a detailed record of your employment dates, employers, and supervisors is critical. Any changes in employment should be documented and certified promptly.
- Gather Documents: Loan statements, tax returns, pay stubs, employment records.
- Utilize Online Tools: StudentAid.gov and PSLF Help Tool are invaluable for tracking and submitting information.
- Communicate with Servicer: Regularly check in with your loan servicer for updates and to confirm your payment counts.
For IDR plans, you will need to reapply or recertify your income and family size annually. This annual recertification is a non-negotiable step to maintain your eligibility and ensure your payments remain affordable. Missing this deadline can lead to higher monthly payments and interest capitalization, which can significantly increase your overall debt burden.
The Department of Education and your loan servicer are your primary resources for guidance. Do not hesitate to contact them with questions or concerns about your application or eligibility. Their role is to assist you through this complex process. Maintaining clear, consistent communication and keeping copies of all submitted documents are best practices that will serve you well.
Future Outlook and Potential Changes for 2026 and Beyond
The future of student loan forgiveness is always subject to political and economic shifts, making it essential for borrowers to remain adaptable and informed. While the core federal programs are expected to continue into 2026, the possibility of new legislation, regulatory changes, or even executive actions always looms. These potential changes could either expand or restrict forgiveness opportunities, highlighting the need for ongoing vigilance.
Discussions around broader student loan relief, including proposals for universal forgiveness or significant overhauls of the current system, are ongoing in policy circles. While the immediate future for 2026 is likely to see the continued operation of existing programs, borrowers should be aware of these larger conversations. Any major legislative breakthroughs could dramatically alter the landscape of student loan debt.
Staying Informed on Policy Developments
One of the best ways to stay ahead of potential changes is to regularly check official government sources, such as the Department of Education’s website and congressional updates. Reputable financial news outlets also often provide timely and accurate reporting on student loan policy developments. Subscribing to newsletters from these sources can help you receive critical information as it becomes available.
- Official Sources: Department of Education, StudentAid.gov.
- Policy Tracking: Follow legislative discussions and proposals related to student debt.
- Financial Advising: Consider consulting a financial advisor specializing in student loans for personalized guidance.
The economic climate also plays a significant role in student loan policy. Periods of economic downturn or recovery can influence the urgency and scope of relief efforts. Understanding these broader trends can provide context for why certain proposals gain traction or why others fade away. Being informed allows you to anticipate potential changes rather than being caught off guard.
Ultimately, while the promise of student loan forgiveness offers significant relief, it requires proactive engagement from borrowers. This means understanding the rules, diligently meeting requirements, and staying informed about any new opportunities or changes. For 2026 and beyond, an informed borrower is an empowered borrower, better equipped to navigate their path to financial freedom from student debt.
| Key Program/Strategy | Brief Description |
|---|---|
| Public Service Loan Forgiveness (PSLF) | Forgives remaining Direct Loan balance after 120 qualifying payments for public service workers. |
| Income-Driven Repayment (IDR) Plans | Adjusts payments based on income; forgiveness after 20-25 years. |
| SAVE Plan | New IDR plan with lower payments and interest subsidies, potentially increasing effective forgiveness. |
| Timely Documentation | Crucial for all applications; includes tax returns, pay stubs, and employment certification. |
Frequently Asked Questions About Student Loan Forgiveness 2026
What types of student loans are eligible for forgiveness in 2026?▼Primarily, federal Direct Loans are eligible for forgiveness programs like PSLF and Income-Driven Repayment plans. Federal Family Education Loans (FFEL) and Perkins Loans may become eligible if consolidated into a Direct Consolidation Loan. Private student loans are generally not eligible for federal forgiveness initiatives.
How can I qualify for an additional 10% in loan forgiveness?▼Qualifying for additional forgiveness often involves leveraging benefits of newer IDR plans like the SAVE plan, which offers lower discretionary income calculations and interest subsidies. Additionally, staying alert for temporary waivers or pursuing specific state/employer-based repayment assistance programs can provide extra relief beyond federal programs.
What is the role of the PSLF Employment Certification Form?▼The PSLF Employment Certification Form is vital for tracking your progress towards Public Service Loan Forgiveness. It verifies your employment with a qualifying organization and ensures your payments are counted correctly. Submitting it annually or whenever you change employers helps avoid delays and ensures accurate record-keeping for your 120 required payments.
Do I need to reapply for my Income-Driven Repayment plan every year?▼Yes, borrowers on Income-Driven Repayment plans must recertify their income and family size annually. This ensures your monthly payments remain accurately calculated based on your current financial situation. Failing to recertify can lead to higher payments and interest capitalization, potentially increasing your loan balance.
What should I do if I have private student loans?▼If you have private student loans, federal forgiveness programs do not apply. You should explore other options such as refinancing with a private lender for a lower interest rate, or contacting your private lender directly to inquire about hardship programs or alternative repayment plans they might offer to assist with your debt.
Conclusion
The journey through student loan debt can be long and challenging, but the opportunities presented by federal forgiveness programs in 2026 offer significant potential for relief. By understanding the nuances of programs like PSLF and the various Income-Driven Repayment plans, including the beneficial SAVE plan, borrowers can strategically navigate their path to financial freedom. Diligent record-keeping, timely application, and continuous engagement with official resources are not just recommendations but necessities for maximizing your chances of forgiveness. Staying informed about policy changes and exploring all available avenues, including potential state or employer-specific programs, can truly make a difference in achieving substantial debt reduction. Take control of your student loan future by being proactive and knowledgeable.